Thor Explorations Announces Positive Pre- Feasibility Study for the Douta Gold Project, Senegal
This announcement contains inside information as defined in the UK version of the Market Abuse Regulation (EU) No.596/2014, which is part of UK domestic law by virtue of the European Union (Withdrawal) Act 2018. Upon the publication of this announcement via a Regulatory Information Service, such inside information will be considered to be in the public domain.
Vancouver, British Columbia--(Newsfile Corp. - January 26, 2026) - Thor Explorations Ltd. (TSXV: THX) (AIM: THX) ("Thor" or the "Company") is pleased to announce the results of its Pre-Feasibility Study ("PFS"), an updated Mineral Resource Estimate (the "Douta Resource" or "MRE") and a maiden Mineral Reserve prepared in accordance with National Instrument 43-101 Standards of Disclosure for Mineral Projects ("NI 43-101") for the 100% owned Douta Gold Project in Senegal ("Douta Project" or the "Project").
The PFS confirms a robust, long-life gold project with strong economics, a substantial Mineral Reserve base, and a clear, accelerated pathway to development - underpinned by significant potential for further resource expansion.
PFS HIGHLIGHTS
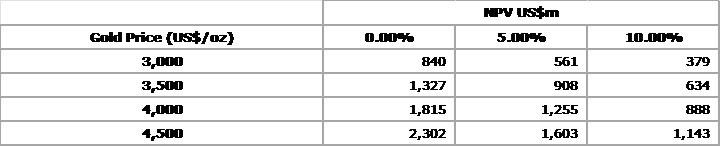
Pre-tax project NPV5% of US$908 million and IRR of 73% (100% equity basis) at a long-term gold price assumption of US$3,500/oz.
Post-tax project NPV5% of US$633 million and IRR of 61% (100% equity basis) at a long-term gold price assumption of US$3,500/oz calculated using statutory Senegalese tax rates and excluding any fiscal incentives expected to be granted under the Mining Convention.
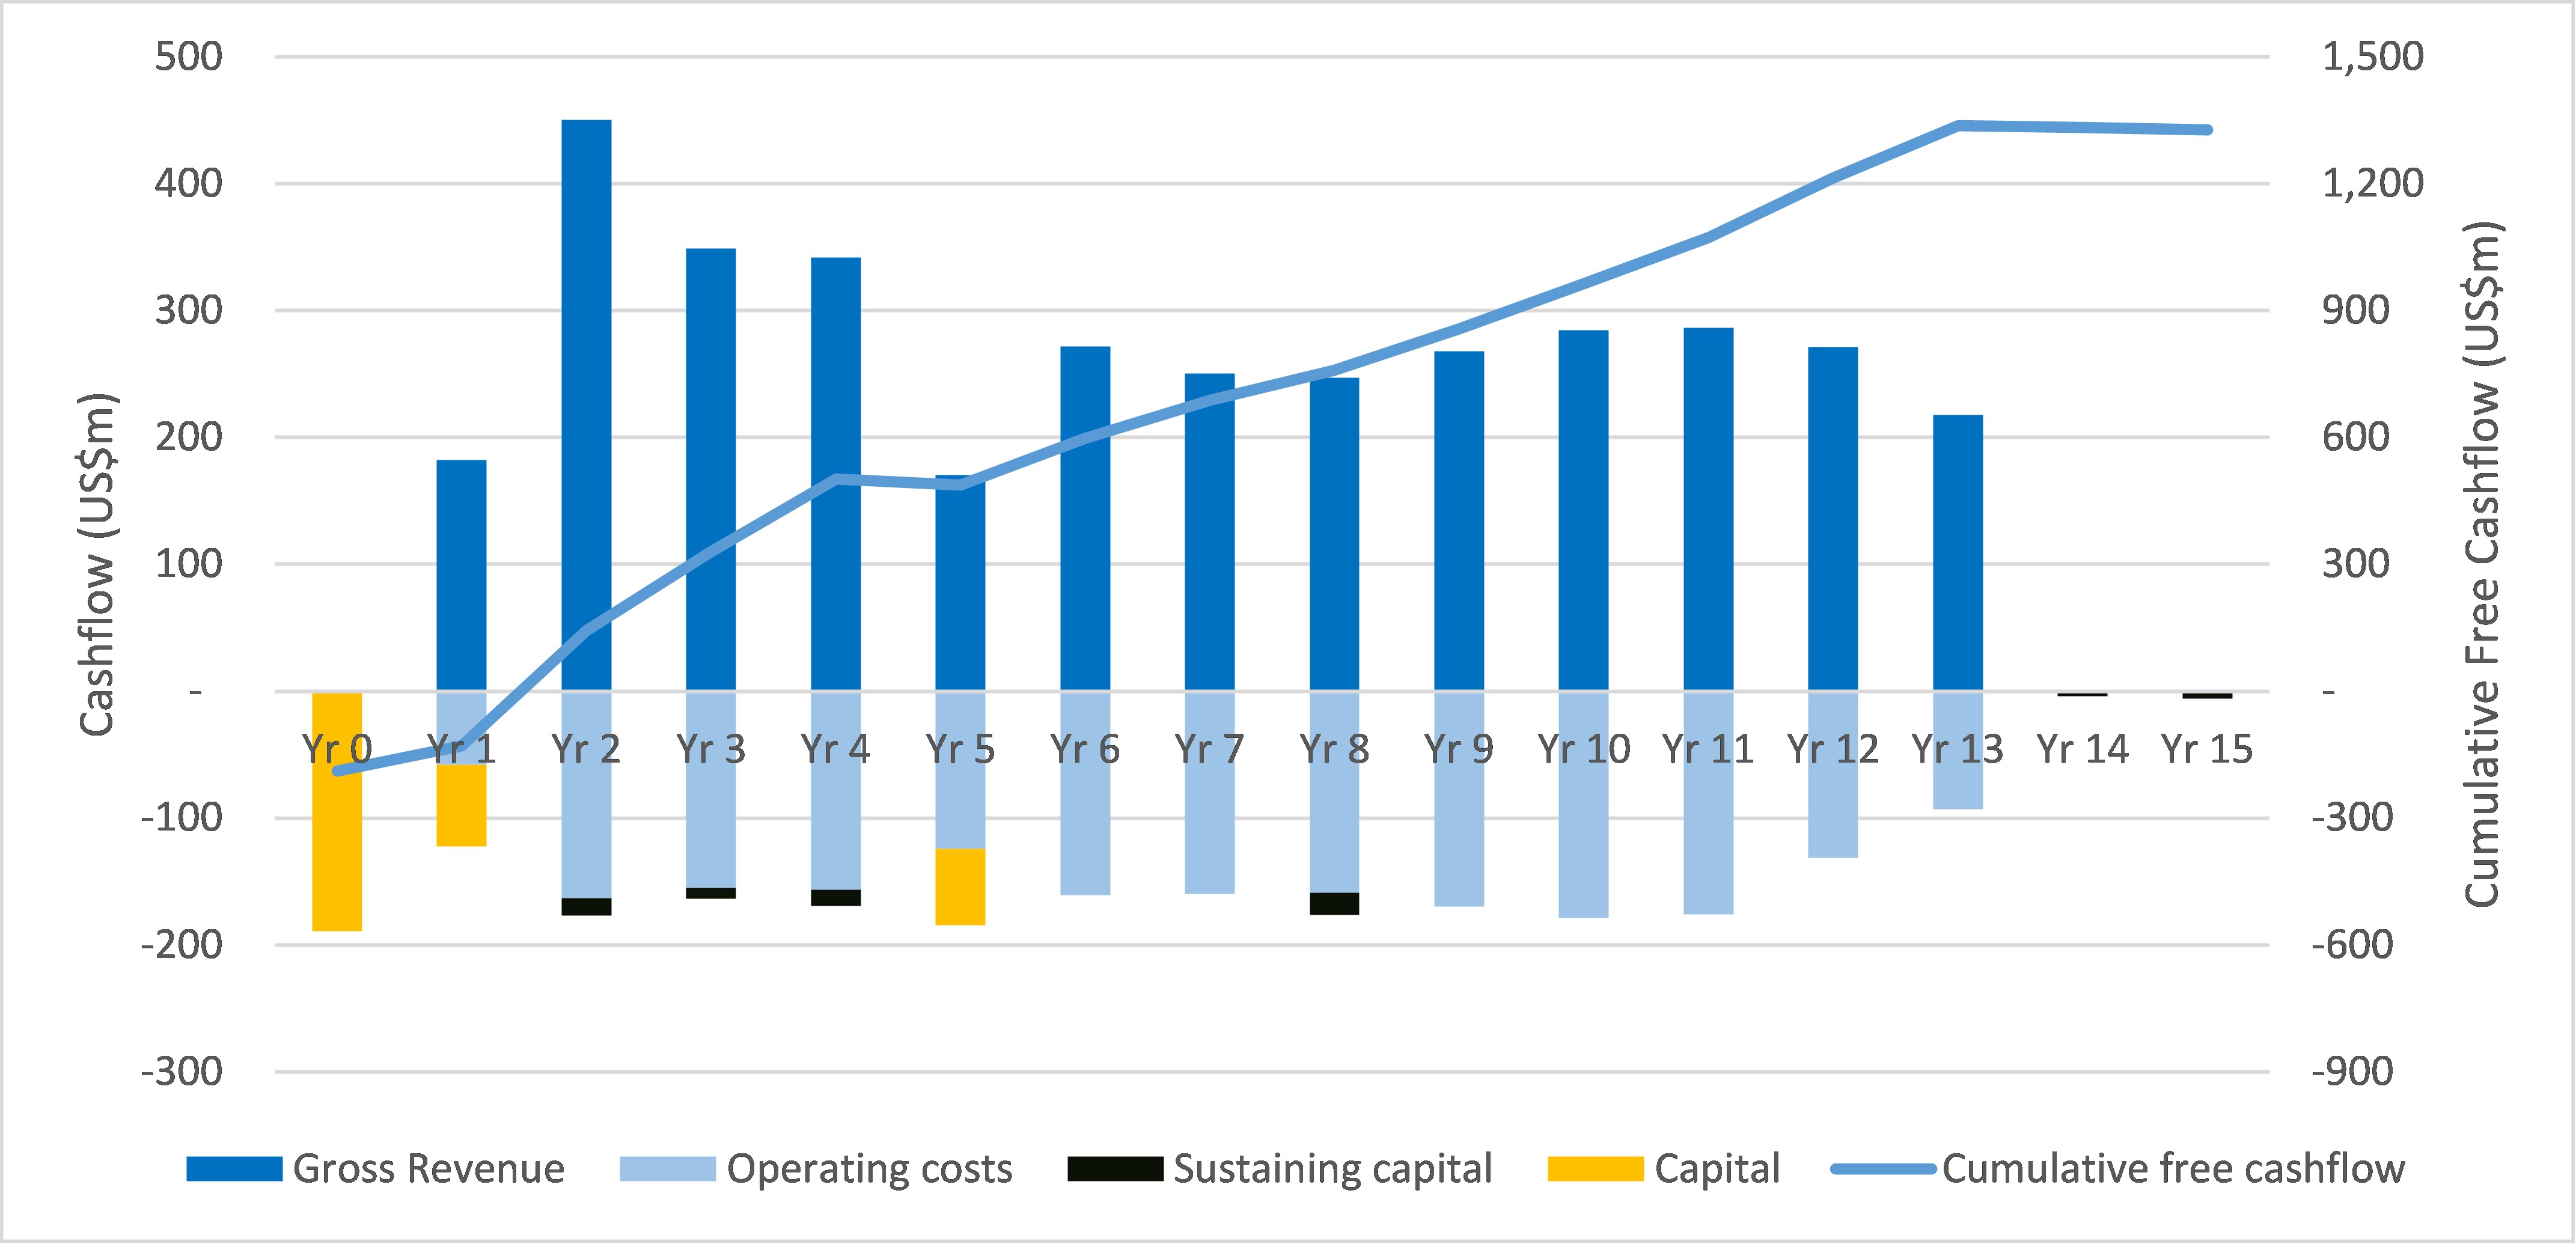
Strong early cashflow, with gold production of 411koz in the first four years of oxide and transitional ore feed ("Oxide Ore Phase") at an all-in sustaining cost ("AISC") of US$1,493/oz, generating a pre-tax cashflow of US$814 million resulting in US$561 million of net cashflow post repayment of Project capital with an anticipated payback period of 11 months following the start of processing.
Significant leverage to higher gold prices - at recent spot gold prices of circa US$4,250/oz the pretax NPV5% increases to US$1.43 billion (100% equity basis) with an IRR of 102% and an anticipated payback of nine months from the start of processing.
Long-life production profile delivering 1.0 million ounces ("Moz") of gold from 37 million tonnes ("Mt") of mill feed grading an average of 1.03 grammes per tonne gold ("g/t Au") (containing 1.2Moz) over 12.6 years of operations.
Two phase production profile comprised of the Oxide Ore Phase and the Primary Ore Phase.
Low initial project capital of US$254 million and Life of Mine ("LOM") AISC of ~US$1,890/oz, supporting strong margins throughout the LOM.
Project is to be entirely funded from the Company's cash reserves and project financing.
The Ministry of Environment approved the Environmental and Social Impact Assessment ("ESIA") in January 2026.
Signed a binding sale and purchase agreement with its Douta-West Permit joint venture partner, Birima Resources SARL ("Birima"), to acquire Birima's entire remaining outstanding 30% in the Douta West Permit for a cash payment of US$1.5 million at signing, a further US$3.5 million at decision to mine and a 1.25% Net Smelter Royalty capped at US$7 million.
Next steps include finalisation of the Mining Convention with the Government of Senegal, commencement of detailed design, ordering of long-lead items and EPC contract award in H1 2026.
The PFS positions Thor to advance its next development project, paving the way to become a multi-asset producer operating across two countries, with first production from Douta targeted for early 2028.
MRE HIGHLIGHTS
Updated Douta MRE constrained within optimised pit shells and comprised of:
Indicated Mineral Resource of 50.6 Mt grading at an average of 1.04 g/t Au for 1.7Moz Au using a long-term gold price of US$4,000; and
Inferred Mineral Resource of 9.3 Mt grading an average of 0.92g/t Au for 273,000oz Au using a long-term gold price of US$4,000.
MRE constitutes a Probable Reserve of 36.6 Mt grading at an average grade of 1.03 g/t Au for 1.2 Moz Au using a long-term gold price of US$3,000 per troy ounce for all mining areas.
The MRE encompasses the Makosa, Makosa Tail and currently, the initial results from the recently discovered Baraka 3 prospects, all of which remain open along strike and down dip.
Ongoing exploration across other prospects, with 40,000 metre drilling program continuing throughout 2026 to delineate additional oxide ore. Mineralisation remains open along strike between the known prospects with further growth potential along the under-explored prospective strike length covered by the Douta permit together with the Douta West and Bousankhoba Permits.
Segun Lawson, President & CEO, stated:
"We are delighted with the results of the Douta PFS which represents a major milestone in our strategy to become a multi-asset gold miner. The results confirm Douta as a high-quality gold project with strong economics, a short payback period and long-term leverage to the gold price through its significant Indicated Resource base.
"The Oxide Ore Phase will produce approximately 413koz in the first four years, during which, the project will have an average annual gold production of over 111koz at an AISC of US$1,469/oz in the first three years.
"At a gold price assumption closer to today's prices (US$4,250/oz) the pre-tax NPV5% and IRR of the Douta Project is approximately US$1.43 billion and 102% respectively (on a 100% basis), paying back the construction capital cost of US$254 million in nine months.
"As per the PFS, Douta will produce approximately 82koz per annum for over 12.6 years at an average AISC of US$1,890/oz.
"In addition to the strong economics, the Project is positioned for further near-term growth in its resource and reserve inventory. Several drilling targets have been delineated through soil, rock chip and auger sampling, and aggressive drilling programs are ongoing, targeting additional oxide resources in the recently acquired contiguous Douta West and Bousankhoba Permits. The continued growth of the Makosa trend and inclusion of the first ounces from the Baraka 3 discovery underscore the district-scale potential of the Douta Project.
"We are currently undertaking our 2026 budgeted 40,000 metre drilling program and aim to update the resource in Q3 this year. We look forward to providing periodic updates of our drilling results.
"Having finished 2025 with a strong cash balance of approximately US$137 million and our continued growing balance sheet in this high gold price environment, we are positioned to fund the construction of Douta without any shareholder dilution and have commenced high level financing discussions with interested parties.
"With simple, low-cost oxide processing in the Oxide Ore Phase, an approved ESIA, and active exploration across multiple prospects, we are strongly positioned to advance Douta towards development while continuing to unlock value across the broader license package.
"We are also pleased to have agreed terms this month and signed a binding agreement with Birima, our Douta-West permit joint venture partner. This acquisition positions us to own the entire Douta Project consisting of the Douta and Douta-West licences on a 100% equity basis and allows for an efficient development process and full exposure to the project economics prior to the Government of Senegal's 10% free carried interest.
"In completing this PFS, we have undertaken a significant amount of work alongside our EPC Contractor, giving us comfort in the EPC pricing and positioning us to fast track to an updated feasibility study. We now look forward to the next steps in developing the Project which include finalisation of our Mining Convention with the Government of Senegal and ordering of the Project's long lead items."
DOUTA PROJECT OVERVIEW
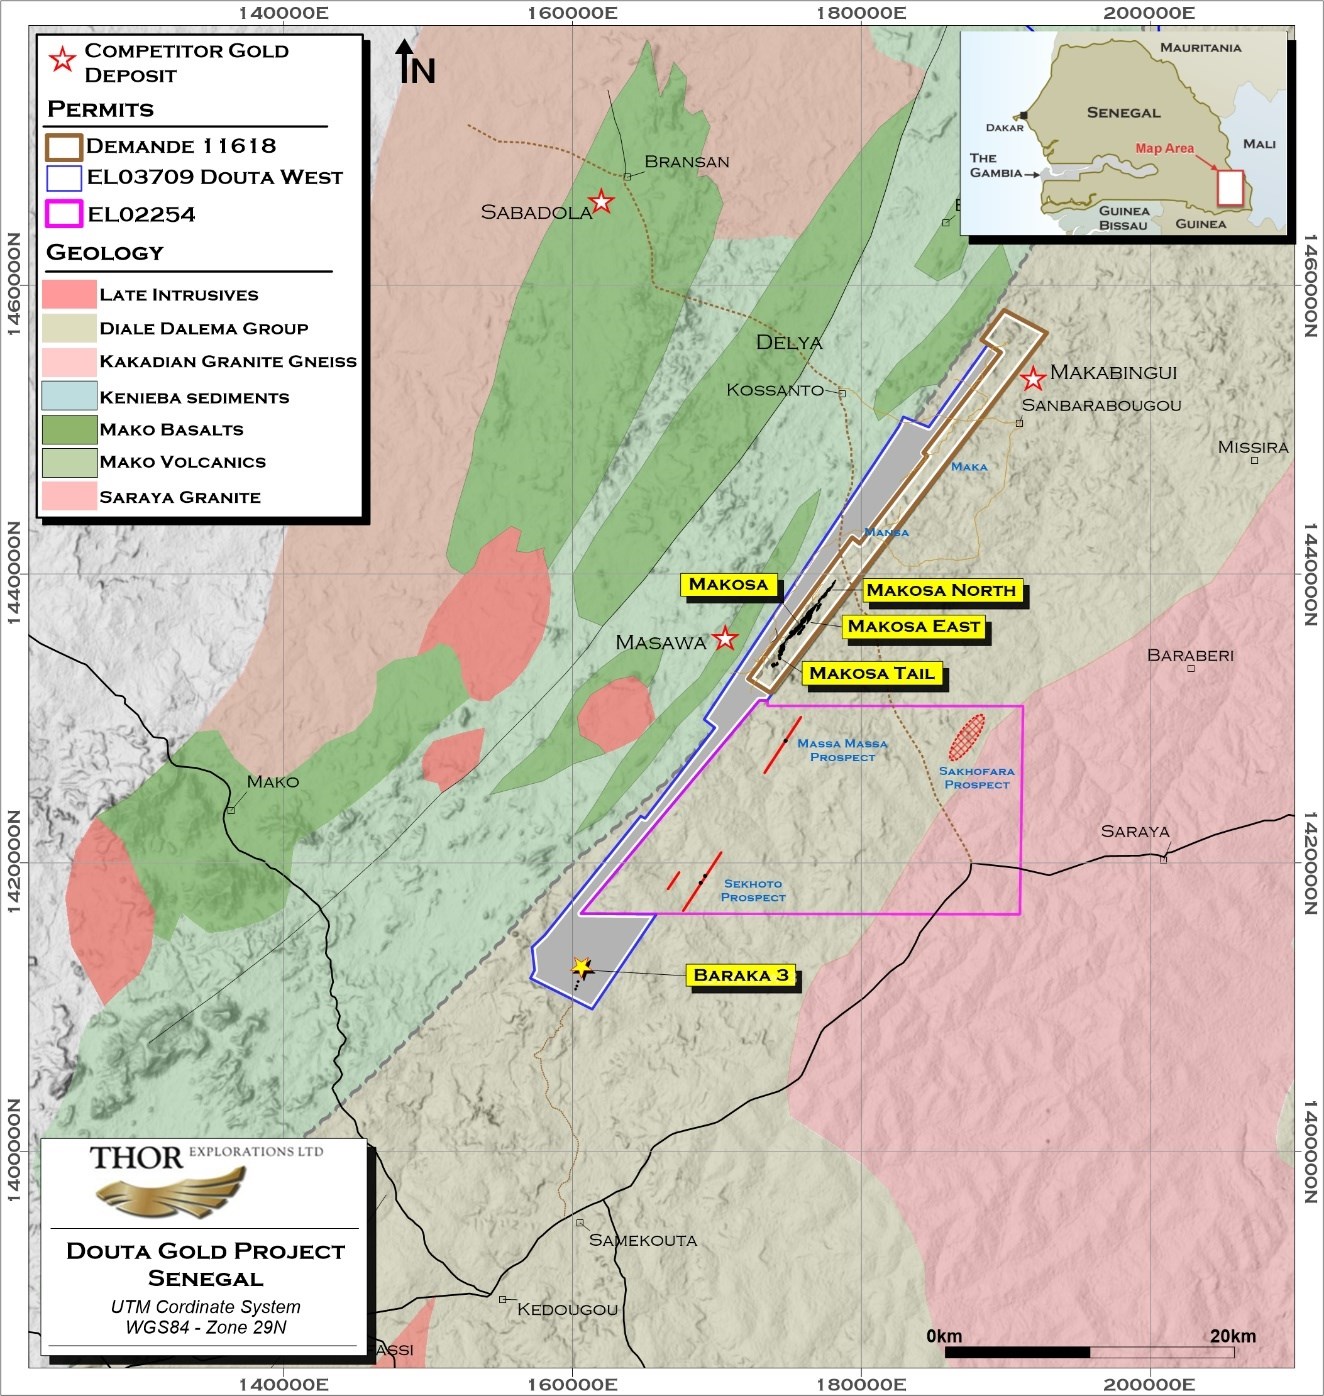
The Douta Project is located within the Birimian rocks of the Kéniéba inlier, in eastern Senegal and comprises the northeast trending mining lease application, De11618 that covers an area of 58 square kilometres ("km2") together with the Douta-West (EL03709) and Bousankhoba (EL02254) exploration permits.
Thor, through its wholly owned subsidiary African Star Resources Incorporated ("African Star"), has a 100% economic interest in both DE11618 and EL03709 which, together, encompass all the known resources that have been defined to date. The recently acquired Bousankhoba permit, in which Thor has 65% interest, covers additional prospective geology along strike from the recently discovered Baraka 3 deposits (Figure 1).
Thor acquired its initial interest in the Douta Project in 2011 and drilled the discovery hole in the deposit in 2012.
Figure 1: Douta Project Location Map
PROJECT OVERVIEW
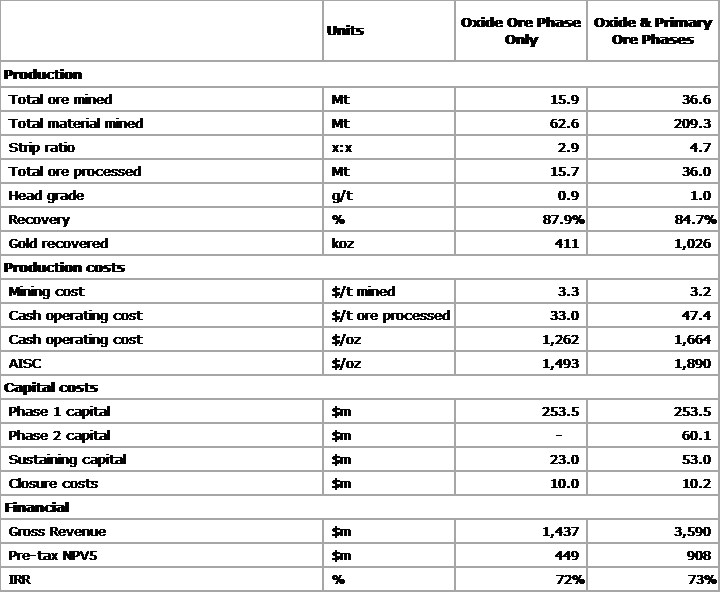
Table 1 includes operational and financial highlights at a flat long-term base-case gold assumption of US$3,500/oz.
Table 1: Economic Summary at US$3,500/oz
Conventional open-pit mining is scheduled to commence at the end of 2027, with plant commissioning and ramp-up during the first quarter of 2028. The Project envisages a 12.6 year LOM, comprising two phases:
Oxide Ore Phase currently spans four years of mining and processing oxide and transitional ores through a conventional Carbon In Leach ("CIL") circuit, delivering average annual production of 103koz.
Primary Ore Phase continues operations for a further 7.8 years, during which fresh ore will be mined and processed through the same CIL circuit enhanced by a suspension roaster, producing an average of 61koz per annum. An additional 2.3 million tonnes of oxide and transitional material, mined during the excavation of the Primary Ore Phase fresh ore pits, is processed for seven months at the end of the mine life, yielding 47koz.
Thor has a strong track record of resource growth at Douta. Ongoing exploration will initially focus on identifying additional oxide material with the aim of extending and enhancing the LOM. If successful, this additional material would likely supplement the Oxide Ore Phase feed and be processed ahead of the Primary Ore Phase.
Figure 2: Production Profile and AISC (US$/oz)
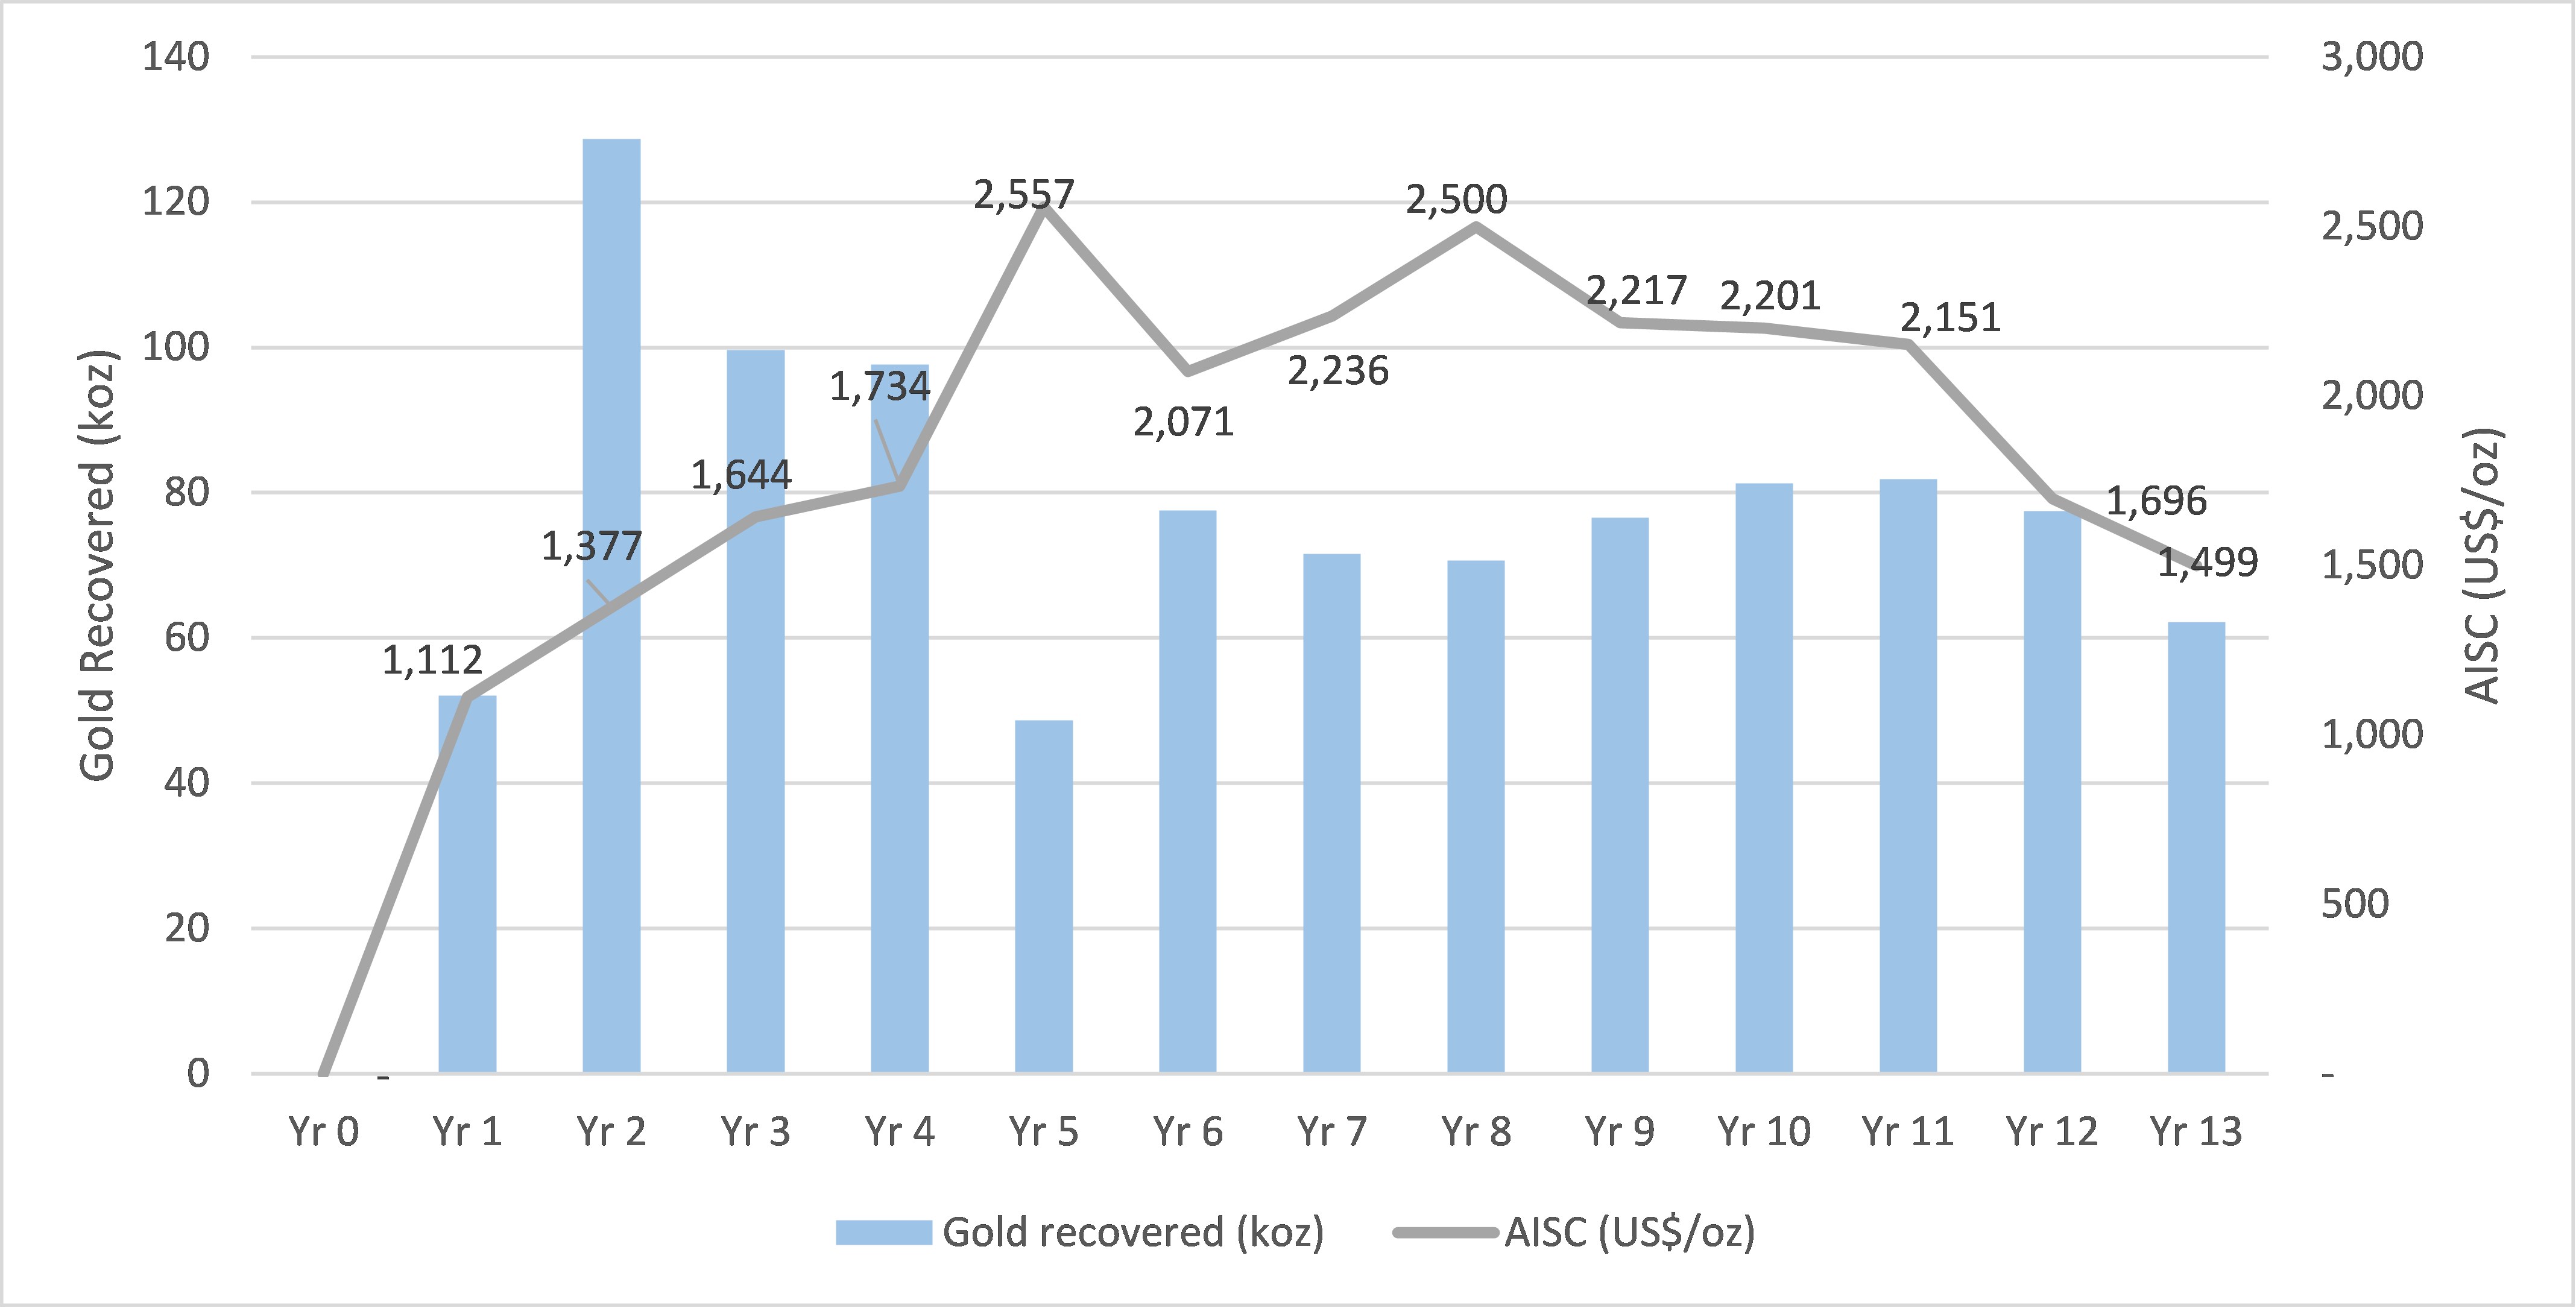
In the first four years of oxide and transitional ore feed, production is 413koz at an AISC of US$1,493/oz. At the base case gold assumption of US$3,500/oz and with a first 18-month production of 180koz, payback would be achieved in one year.
Figure 3: Free Cash Flow Profile (US$m)
The pre-tax NPV sensitivity comparing varying discount rate percentages and gold price is presented in Table 2. The base case result for the Project is highlighted in bold.
Table 2: Sensitivity of pre-tax NPV5% (US$M) to Discount Rate and Gold Price (US$/oz) (Base case US$3,500/oz)
The post-tax NPV sensitivity comparing varying discount rate percentages and gold price is presented in Table 3. The base case result for the Project is highlighted in bold.
Table 3: Sensitivity of post-tax NPV5% (US$M) to Discount Rate and Gold Price (US$/oz) (Base case US$3,500/oz)
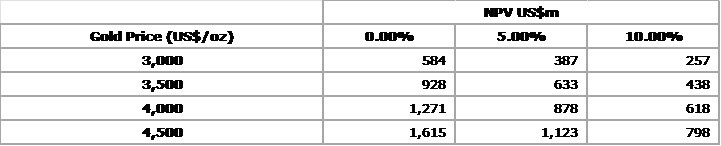
The Post-tax results exclude fiscal incentives expected under the Mining Convention. Tax has been modelled using a standard loss-pool approach with the statutory 30% corporate tax rate. The 10% State free-carried interest required under Senegalese law is not yet applied and will be incorporated after the Mining Convention is agreed.
MINERAL RESOURCES AND RESERVES ESTIMATES
MINERAL RESOURCE ESTIMATE
The MRE encompasses the Makosa, Makosa Tail and Baraka 3 Prospects, which are collectively referred to as the Douta Project.
The MRE is based on data obtained from a total of 69,598 metres ("m") of drilling comprising 2,936m of diamond drilling and 66,662m of Reverse Circulation ("RC") drilling.
The MRE is reported at a cut-off grade of 0.3g/t Au within optimised shells using a gold price of US$4,000.
| Classification | Tonnes (Mt) | Grade (g/tAu) | Contained Gold (Moz) |
|---|---|---|---|
| Indicated | 50.6 | 1.04 | 1.7 |
| Inferred | 9.3 | 0.92 | 0.27 |
Table 4: Douta Gold Project Total Classified Mineral Resource Estimate Summary, January 2026 (reported at cut-off grade of 0.3g/t Au)
| Classification | Weathering Zone | Code | Tonnage (MT) | Grade (g/tAu) | Contained Gold (Moz) |
|---|---|---|---|---|---|
| Indicated | Strongly Oxidised | SOX | 1.3 | 1.09 | 0.05 |
| Indicated | Moderately Oxidised | MOX | 9.4 | 1.02 | 0.31 |
| Indicated | Weakly Oxidised | WOX | 7.3 | 1.01 | 0.24 |
| Indicated | Fresh | FRS | 32.6 | 1.06 | 1.11 |
| Indicated | Total | 50.6 | 1.04 | 1.70 |
| Classification | Weathering Zone | Code | Tonnage (MT) | Grade (g/tAu) | Contained Gold (Moz) |
|---|---|---|---|---|---|
| Inferred | Strongly Oxidised | SOX | 0.1 | 0.64 | 0.00 |
| Inferred | Moderately Oxidised | MOX | 1.2 | 0.67 | 0.03 |
| Inferred | Weakly Oxidised | WOX | 0.6 | 0.72 | 0.01 |
| Inferred | Fresh | FRS | 7.4 | 0.98 | 0.23 |
| Inferred | Total | 9.3 | 0.92 | 0.27 |
Table 5: Douta Gold Project Total Classified Mineral Resource Estimate Summary by Weathering Zone, January 2026 (reported at cut-off grade of 0.3g/t Au)
| Classification | Deposit | Tonnage (MT) | Grade (g/t Au) | Contained Gold (Moz) | Thor Interest % |
|---|---|---|---|---|---|
| Indicated | Makosa North | 9.9 | 1.08 | 0.34 | 100 |
| Indicated | Makosa | 20.6 | 1.06 | 0.70 | 100 |
| Indicated | Makosa East | 8.3 | 0.92 | 0.25 | 100 |
| Indicated | Makosa Tail | 10.6 | 1.03 | 0.35 | 100 |
| Indicated | Baraka 3 | 1.1 | 1.43 | 0.05 | 100 |
| Indicated | Total | 50.6 | 1.04 | 1.70 |
| Classification | Deposit | Tonnage (MT) | Grade (g/t Au) | Contained Gold (Moz) | Thor Interest % |
|---|---|---|---|---|---|
| Inferred | Makosa North | 4.8 | 1.02 | 0.16 | 100 |
| Inferred | Makosa | 1.5 | 0.95 | 0.05 | 100 |
| Inferred | Makosa East | 1.3 | 0.87 | 0.04 | 100 |
| Inferred | Makosa Tail | 1.4 | 0.57 | 0.03 | 100 |
| Inferred | Baraka 3 | 0.2 | 0.99 | 0.01 | 100 |
| Inferred | Total | 9.3 | 0.92 | 0.27 |
Table 6: Douta Gold Project Mineral Resource Estimate by Area, January 2026 (reported at cut- off grade of 0.3g/t Au
| Classification | Deposit | Code | Tonnage (MT) | Grade (g/tAu) | Contained Gold (x1000oz) |
|---|---|---|---|---|---|
| Indicated | Makosa North | SOX | 0.1 | 1.08 | 4 |
| Indicated | Makosa North | MOX | 2.0 | 1.10 | 70 |
| Indicated | Makosa North | WOX | 2.0 | 1.11 | 72 |
| Indicated | Makosa North | FRESH | 5.8 | 1.06 | 197 |
| Indicated | Makosa North | Total | 9.9 | 1.08 | 342 |
| Indicated | Makosa | SOX | 1.0 | 1.11 | 36 |
| Indicated | Makosa | MOX | 2.9 | 1.08 | 100 |
| Indicated | Makosa | WOX | 2.1 | 1.06 | 72 |
| Indicated | Makosa | FRESH | 14.6 | 1.06 | 496 |
| Indicated | Makosa | Total | 20.6 | 1.06 | 704 |
| Indicated | Makosa East | SOX | 0.1 | 0.93 | 4 |
| Indicated | Makosa East | MOX | 2.1 | 0.85 | 56 |
| Indicated | Makosa East | WOX | 1.7 | 0.84 | 45 |
| Indicated | Makosa East | FRESH | 4.5 | 0.98 | 141 |
| Indicated | Makosa East | Total | 8.3 | 0.92 | 246 |
| Indicated | Makosa Tail | SOX | 0.1 | 0.79 | 1 |
| Indicated | Makosa Tail | MOX | 1.8 | 0.88 | 49 |
| Indicated | Makosa Tail | WOX | 1.4 | 0.93 | 43 |
| Indicated | Makosa Tail | FRESH | 7.5 | 1.09 | 261 |
| Indicated | Makosa Tail | Total | 10.7 | 1.03 | 355 |
| Indicated | Baraka3 | SOX | 0.0 | 1.60 | 2 |
| Indicated | Baraka3 | MOX | 0.7 | 1.42 | 34 |
| Indicated | Baraka3 | WOX | 0.2 | 1.35 | 9 |
| Indicated | Baraka3 | FRESH | 0.2 | 1.53 | 8 |
| Indicated | Baraka3 | Total | 1.1 | 1.43 | 53 |
| Total | 50.6 | 1.04 | 170 |
Table 7: Douta Gold Project Mineral Resource Estimate by Area and Weathering Zone, January 2026 (reported at cut-off grade of 0.3g/t Au)
| Classification | Deposit | Code | Tonnage (MT) | Grade (g/tAu) | Contained Gold (x1000oz) |
|---|---|---|---|---|---|
| Inferred | Makosa North | SOX | 0.0 | 0.61 | 0.1 |
| Inferred | Makosa North | MOX | 0.1 | 0.68 | 1.9 |
| Inferred | Makosa North | WOX | 0.1 | 0.68 | 1.5 |
| Inferred | Makosa North | FRESH | 4.7 | 1.03 | 154.9 |
| Inferred | Makosa North | Total | 4.8 | 1.02 | 158.3 |
| Inferred | Makosa | SOX | 0.0 | 0.62 | 0.6 |
| Inferred | Makosa | MOX | 0.3 | 0.73 | 5.9 |
| Inferred | Makosa | WOX | 0.1 | 0.77 | 3.6 |
| Inferred | Makosa | FRESH | 1.1 | 1.03 | 35.5 |
| Inferred | Makosa | Total | 1.5 | 0.95 | 45.6 |
| Inferred | Makosa East | SOX | 0.0 | 0.53 | 0.4 |
| Inferred | Makosa East | MOX | 0.4 | 0.65 | 7.5 |
| Inferred | Makosa East | WOX | 0.2 | 0.81 | 4.6 |
| Inferred | Makosa East | FRESH | 0.8 | 0.99 | 25.1 |
| Inferred | Makosa East | Total | 1.3 | 0.87 | 37.5 |
| Inferred | Makosa Tail | SOX | 0.0 | 0.52 | 0.5 |
| Inferred | Makosa Tail | MOX | 0.3 | 0.50 | 5.3 |
| Inferred | Makosa Tail | WOX | 0.3 | 0.62 | 5.0 |
| Inferred | Makosa Tail | FRESH | 0.8 | 0.58 | 15.1 |
| Inferred | Makosa Tail | Total | 1.4 | 0.57 | 25.8 |
| Inferred | Baraka3 | SOX | 0.0 | 1.09 | 0.5 |
| Inferred | Baraka3 | MOX | 0.2 | 0.98 | 5.1 |
| Inferred | Baraka3 | WOX | 0.0 | 0.88 | 0.3 |
| Inferred | Baraka3 | FRESH | 0.0 | 1.27 | 0.1 |
| Inferred | Baraka3 | Total | 0.2 | 0.98 | 6.0 |
| Total | 9.3 | 0.92 | 273.2 |
Open Pit Mineral Resources are reported in situ at a cut-off grade of 0.30 g/t Au. An optimised Whittle shell (US$4,000) was used to constrain the resources.
The Mineral Resource is considered to have reasonable prospects for economic extraction by open pit mining methods above a 0.30 g/t Au and within an optimised pit shell.
Cut-off grade varied from 0.27 g/t to 0.30 g/t in a pit shell based on mining costs, metallurgical recovery, milling costs and G&A costs. Metallurgical and mining recovery factors have been applied.
Mineral Resources are not Mineral Reserves and do not have demonstrated economic viability.
Totals may not add exactly due to rounding.
Resources reported as totals, minor equity portion is not deducted.
The statement used the terminology, definitions and guidelines given in the CIM Standards on Mineral resources and Mineral Reserves (May 2014) as required by NI 43-101.
Bulk density is assigned according to weathering profile with a weighted average of 2.78.
The resource estimate was prepared by Mr Alfred Gillmam, who is a qualified person ("QP") under NI 43-101and is not independent of the Company.
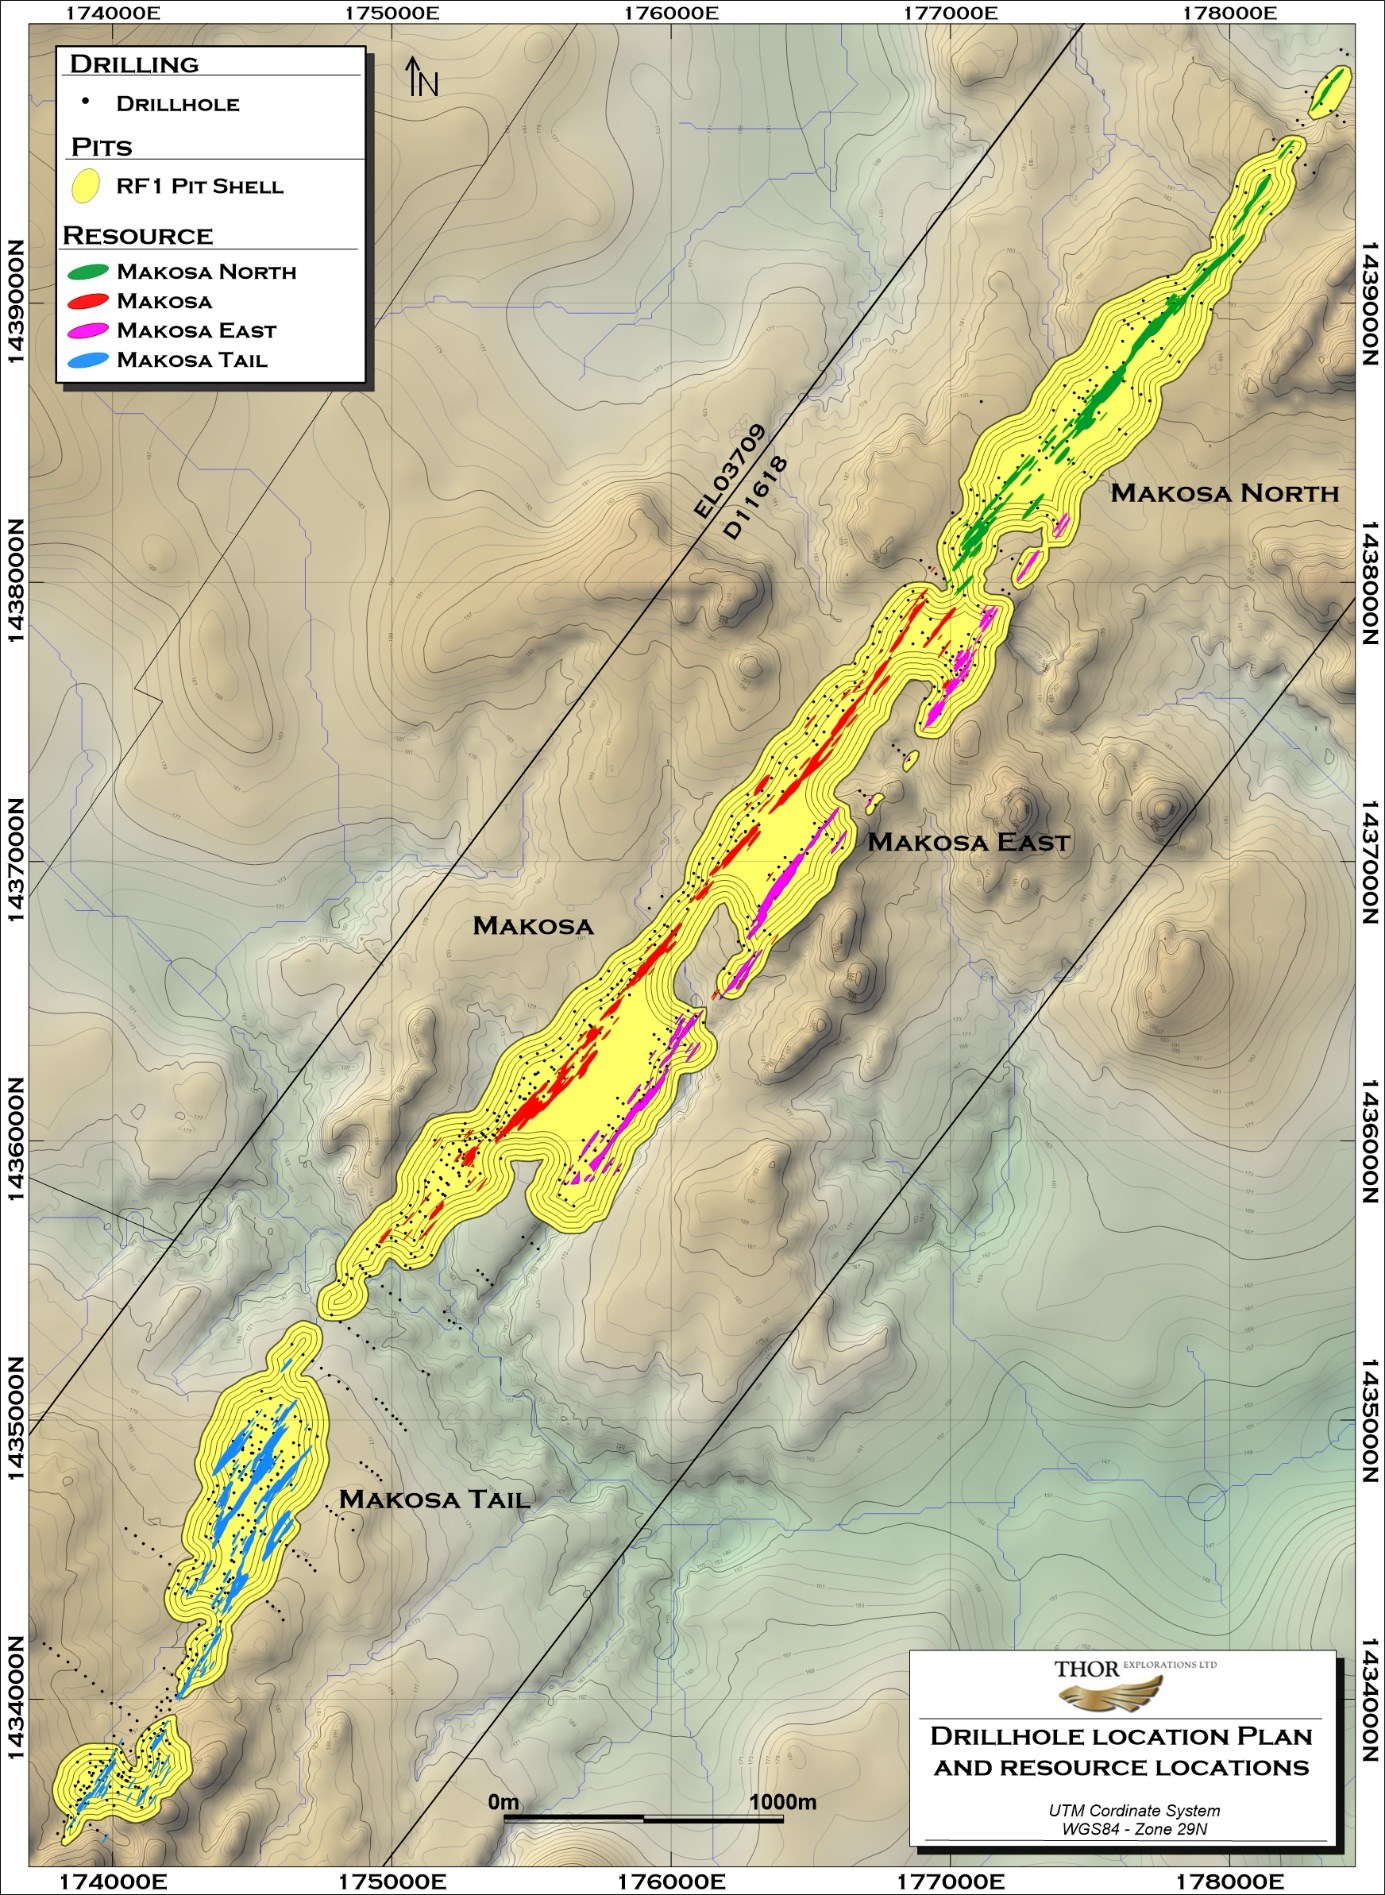
Mineral Resources for the Douta Project are estimated for five gold deposits and prospects located on the Douta and the Douta West exploration permit (Figure 1). Separate blocks models cover the Makosa, Makosa Tail, and Baraka 3 deposits. The Makosa block model encompasses the Makosa, Makosa North, and Makosa East deposits. Mineral Resources are reported inclusive of Mineral Reserves at an effective date of 24 January 2026 (Table 4).
The methods, parameters, assumptions, and support data used for the Douta block models, which date back to 2023, were reviewed to ensure they remain current. Models have been updated as required to either include new information or revised cost assumptions such as gold price and operation costs.
The same overall approach was used for each model whereby block grade and density estimates are constrained by domains representing the mineralisation, lithology, and weathering surfaces. Mineral Resources are reported within pit shells generated by AMC Consultants. Only classified blocks greater than or equal to the open pit cut-off grades and within the open pit shells are reported.
MINERAL RESERVE
Table 8 shows a summary of the Douta Project Mineral Reserves, which have been reported in accordance with CIM standards.
Table 8: Summary of Mineral Reserve Estimate for the Douta Project
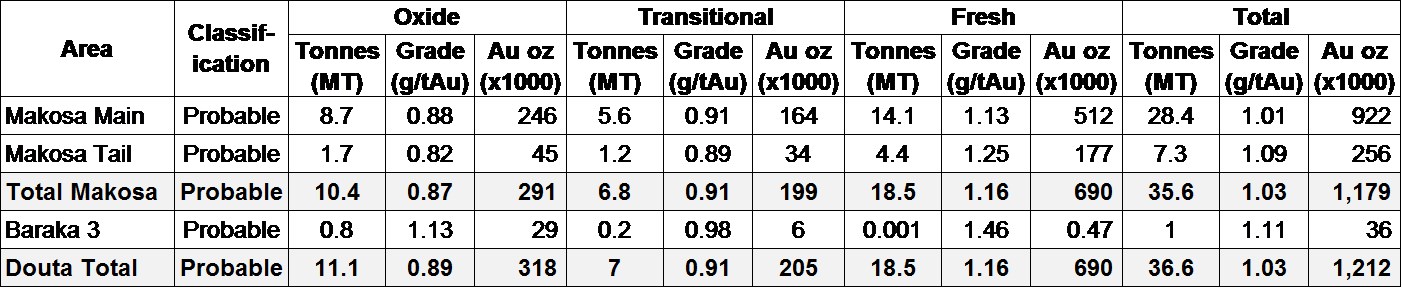
CIM Definition Standards for Mineral Resources and Mineral Reserves (CIM, 2014) were used for reporting of Mineral Reserves.
Mineral Reserves are estimated using a long-term gold price of US$3,000 per troy ounce for all mining areas.
Mineral Reserves are stated in terms of delivered tonnes and grade before process recovery.
Mineral Reserves are defined by pit optimisation and engineered pit design.
Mineral Reserves are based on variable break-even cut-offs as generated by metallurgical recoveries and costs. Baraka 3 also incurs an ore haulage cost due to its distance from the proposed processing plant.
Cut-off grades range from 0.28 g/t to 0.51 g/t for Makosa and 0.35 g/t to 0.43 g/t for Baraka 3.
Metal recoveries are variable dependent on material type and mining area.
Open-pit dilution and geological ore loss is applied through the regularisation of the Mineral Resource model to pre-determined Selective Mining Unit (SMU) blocks.
The Mineral Reserve estimate was undertaken using the Deswik mine planning software (Version 2025.2) and demonstrated that mining of the Makosa, Makosa Tail and Baraka 3 deposits at the Douta project is practical and economically viable.
The effective date of Mineral Reserves is January 2026.
Tonnage and grade measurements are in metric units. Contained Au is reported as troy ounces.
The Mineral Reserve estimate was prepared by Mr Dominic Claridge of AMC Consultants, who is a qualified person ("QP") under NI 43- 101and is independent of the Company.
TECHNICAL AND MODIFYING FACTORS
Sample Analysis and Database
Drilling has been almost exclusively sampled on 1m intervals with the main laboratory for analysis being ALS Global's laboratory in Bamako, Mali. Split samples ranging in weight from 0.5 kilogram ("kg") to 3.5kg, with an average of 2.3kg were collected for analysis. After the sample preparation a fire assay with an atomic absorption finish on a 50 grammes subsample of the pulp (AA26), was completed. Standard QA/QC protocols were followed with inserts of certified standards, blanks and duplicates representing approximately 10% of all analyses. The Company's DataShed5 database is maintained by MaxGeo (Western Australia).
Estimation Parameters
An Inverse Distance grade estimation was carried out within hard geological boundaries defined by a numerical model. Ordinary Kriging has been used to validate the Inverse Distance estimation results.
Separate numerical models were generated for Makosa Tail, Makosa North and East and Baraka 3.
A weathering model was developed to assign bulk densities based on weathering state.
Managing High Grade Samples
A capping level (top cut) of 10g/t Au is applied to all Makosa domains. An 8g/t Au top cut was applied to the Baraka 3 grade estimates.
Figure 4: Makosa Resource Area Location Map